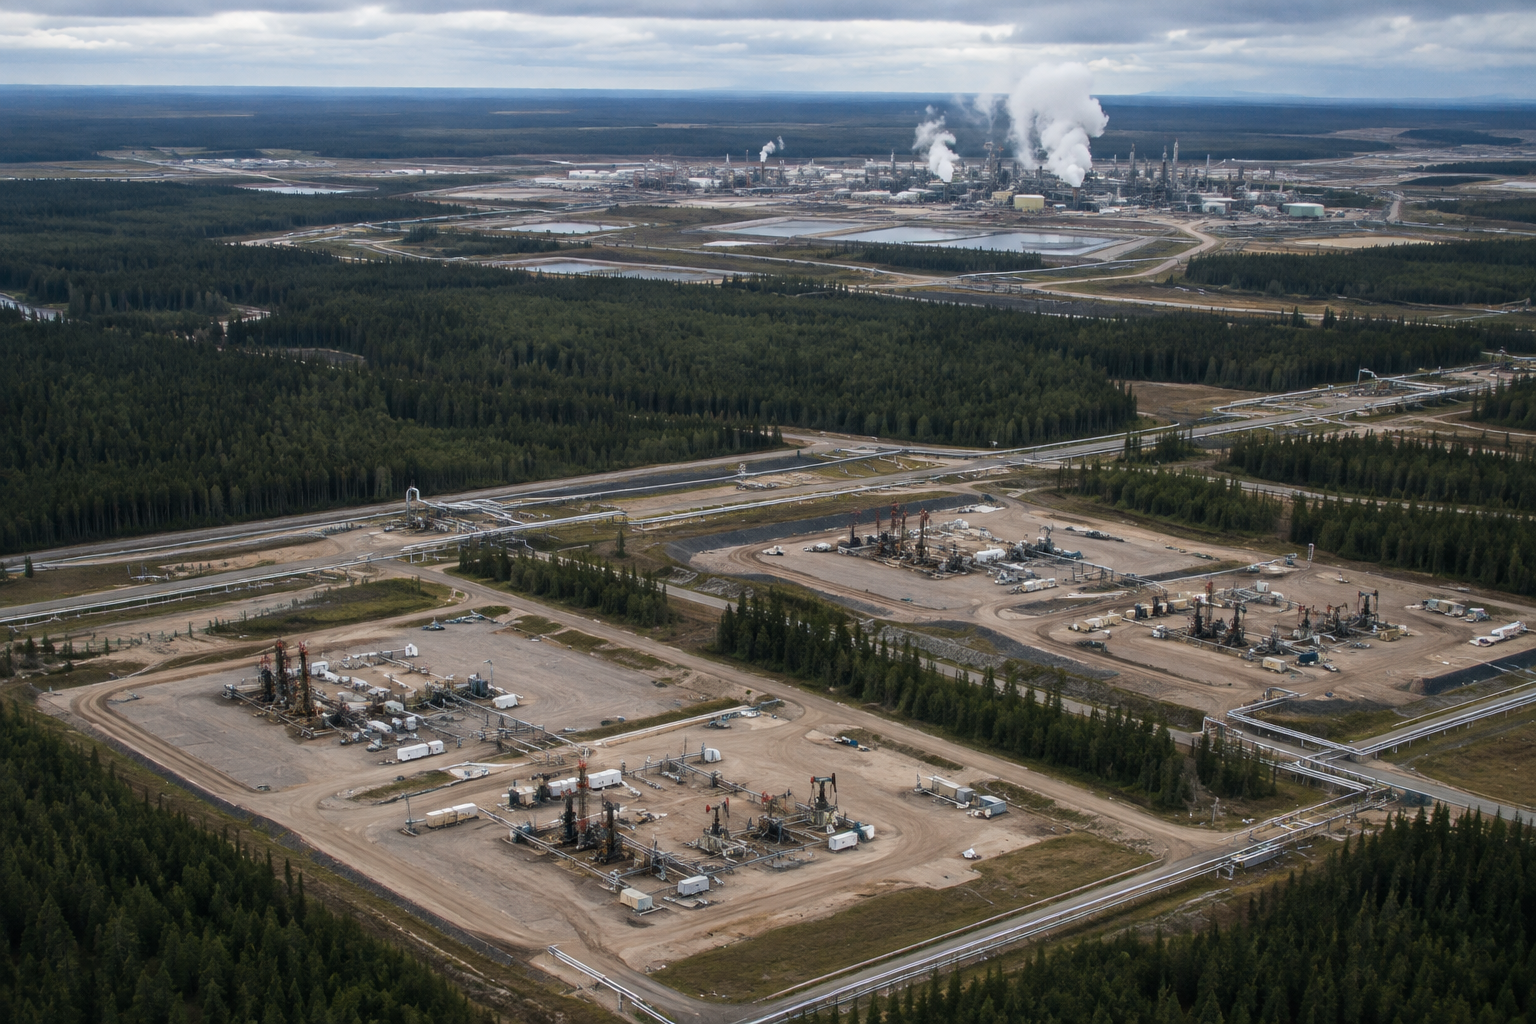
Canada’s oil sands are getting a new map. Cenovus Energy Inc. has entered a definitive arrangement agreement to acquire Athabasca Oil Corporation in a $5.7 billion cash-and-stock transaction, creating one of the sector’s most consequential consolidation moves in recent Canadian energy markets.
The deal places Cenovus’s dual-listed shares—$CVE on the TSX and NYSE—at the center of a transaction that also directly affects Athabasca’s TSX-listed $ATH shares. For investors, this is more than a corporate combination: it is a fresh test of how Canadian upstream-energy companies navigate scale, oil-price volatility and the market’s appetite for oil sands exposure.
A cash-and-stock wager on scale
The announced transaction is structured as a cash-and-stock deal and carries a reported value of $5.7 billion. The company release describes an implied enterprise value, making the precise transaction framework and underlying assumptions especially important for shareholders parsing the announcement.
Readers looking for the formal terms should turn to Cenovus’s company announcement and the corresponding Athabasca announcement. Those releases are the appropriate reference points for the arrangement’s transaction details, rather than treating the headline value as a complete description of the consideration or enterprise-value calculation.
Strategically, the logic is familiar but still powerful: combine assets and operations in a capital-intensive part of the energy industry, where scale may matter when crude prices are moving unpredictably. The acquisition would bring Athabasca into Cenovus’s broader corporate orbit, turning two publicly traded Canadian oil sands stories into one larger strategic narrative.
Why this matters for the oil sands
The transaction represents a major consolidation event in the Canadian energy sector and, more specifically, in the oil sands. Consolidation can change how investors view an industry: instead of evaluating companies solely as separate production and balance-sheet stories, the market begins to focus on the advantages and trade-offs of greater corporate scale.
That does not make the outcome automatic. A larger company may have more room to coordinate assets and pursue efficiencies, but shareholders still have to assess how the cash-and-stock structure distributes value between the two shareholder groups. The $5.7 billion figure provides the headline; the arrangement mechanics will determine how that headline translates into ownership, consideration and exposure.
The deal also arrives as Canadian upstream-energy merger and acquisition activity continues to draw attention amid oil-price volatility. Volatile commodity markets can make corporate scale look attractive, while simultaneously raising the stakes around capital allocation and operating execution. In that setting, the Athabasca acquisition reads as both a strategic expansion and a statement about the continuing relevance of Canadian oil sands assets.
Three share-price stories, one transaction
For holders and traders of Cenovus’s $CVE shares, the transaction may sharpen the market’s focus on the company’s ability to absorb a major acquisition while maintaining a clear strategic identity. Because Cenovus trades on both the TSX and NYSE, the same corporate event will be watched across two North American trading venues. The listings offer different market contexts, but they represent exposure to the same announced acquisition.
Athabasca’s $ATH shares carry a different kind of event sensitivity. As the target company’s TSX-listed shares, they may become a direct market gauge of how investors interpret the proposed consideration and the path toward completion. That does not remove uncertainty: the transaction remains an arrangement agreement, and the relevant terms, conditions and approvals outlined in the company announcements will matter.
For Canadian energy investors, the broader takeaway is that oil sands consolidation remains an active force in the market’s story. Cenovus’s move to acquire Athabasca may reshape how investors compare scale, commodity exposure and corporate positioning across the sector. The market will now have to decide whether the combination’s strategic promise outweighs the complexity that comes with a large cash-and-stock transaction in a volatile oil environment.
Bull/Bear Verdict
Bull Case: The $5.7 billion cash-and-stock acquisition may give Cenovus greater scale in the Canadian oil sands and could strengthen the strategic case for consolidation amid oil-price volatility.
Bear Case: The transaction’s implied enterprise value and arrangement mechanics may leave investors focused on execution, consideration details and the uncertainty facing both $CVE and $ATH in a volatile commodity market.