Diamondback Energy has placed a $5 billion marker in the Permian Basin, confirming an agreement to acquire holdings from Double Eagle on November 16, 2026. For the US energy sector, the transaction is more than a corporate expansion: it is another sign that the industry’s most valuable shale real estate remains a central battleground for scale.
For shareholders in $FANG, the deal puts the Permian at the center of the company’s strategic story. It also gives investors a fresh lens through which to view acreage valuations, oilfield-services demand and the broader question of how US shale companies deploy capital in a mature, increasingly consolidated market.
A $5 Billion Vote on Permian Importance
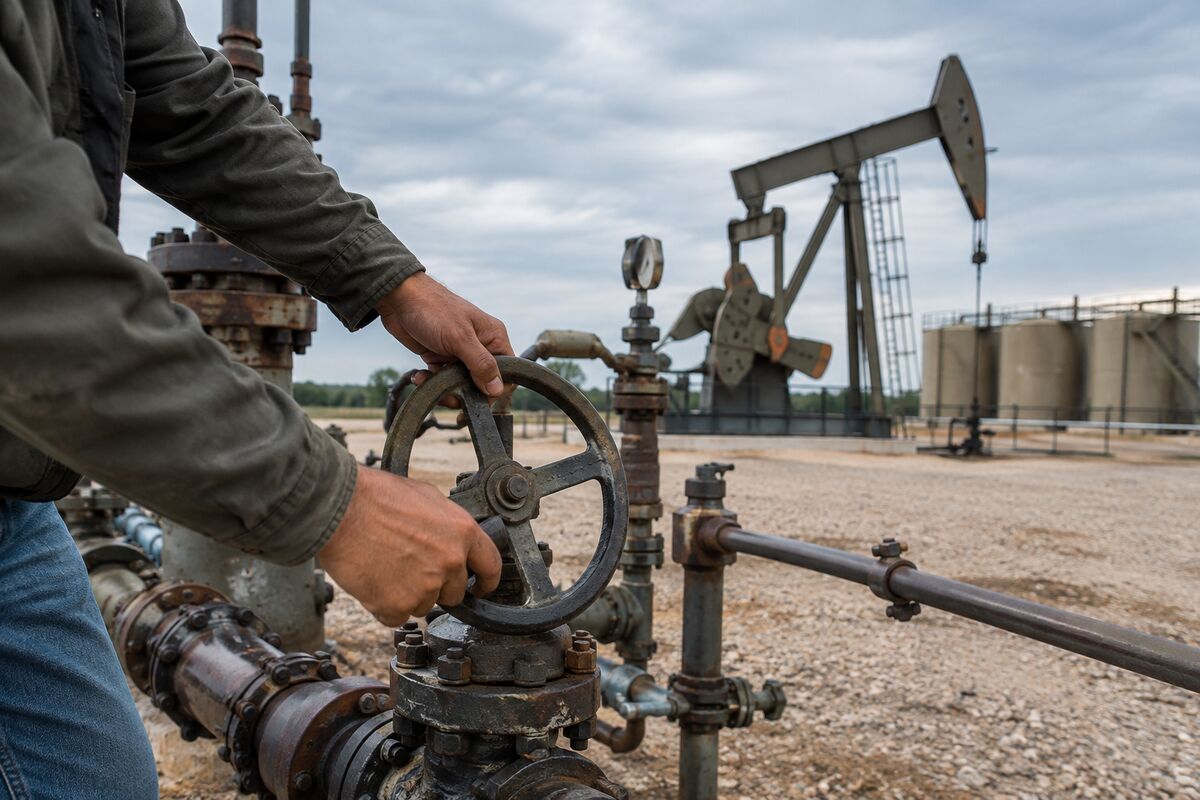
The confirmed acquisition is explicitly focused on Permian Basin holdings, making the basin the transaction’s central asset and strategic focus. While the announcement does not provide production volumes, financing details, closing conditions or expected synergies, the headline value alone makes the deal a notable data point for the US energy market.
A $5 billion transaction may influence how market participants frame the value of comparable Permian acreage. It does not establish a universal price for every parcel, since geology, infrastructure and operating characteristics can differ substantially. Still, a deal of this size could become a reference point in discussions about what premium basin assets may command when a buyer is willing to commit significant capital.
Consolidation’s Next Chapter
US shale has spent years moving from a landscape of aggressive growth toward one where scale and asset concentration matter more. Diamondback’s agreement with Double Eagle contributes to that continuing consolidation. The logic is straightforward: fewer, larger operators may have greater control over strategic acreage and a larger platform from which to manage development decisions.
That does not make consolidation automatically beneficial for every participant. For the industry, the important question is how each transaction changes competitive dynamics and capital allocation. The Double Eagle purchase indicates that, at least in this case, a major operator sees strategic value in adding Permian holdings at a $5 billion price tag.
Ripple Effects Across the Energy Chain
Oilfield-services companies may also watch the transaction closely. Additional concentration of Permian ownership could affect where drilling and completion activity is directed, although the announcement does not disclose any production or development timetable. The potential implication is less about an immediate volume forecast and more about the bargaining landscape created when a large operator controls more of a key US basin.
For energy investors, the deal also sharpens the debate over capital allocation. A major acquisition commits substantial resources to existing US shale geography rather than leaving capital entirely with smaller operators or directing it elsewhere. Whether that approach proves attractive will depend on future execution and market conditions, neither of which is detailed in the announcement.
The confirmed transaction, reported by Seeking Alpha, therefore carries significance beyond the two companies involved. It is a visible signal that Permian acreage remains important enough to anchor multibillion-dollar corporate strategy—and that US shale consolidation still has room to reshape the sector.
Bull/Bear Verdict
Bull Case: The $5 billion acquisition could strengthen $FANG’s strategic position in the Permian Basin while reinforcing the value of scale and high-quality US shale acreage.
Bear Case: The $5 billion commitment could increase scrutiny of capital allocation, while the absence of disclosed production, financing and synergy details leaves the transaction’s eventual impact uncertain.